
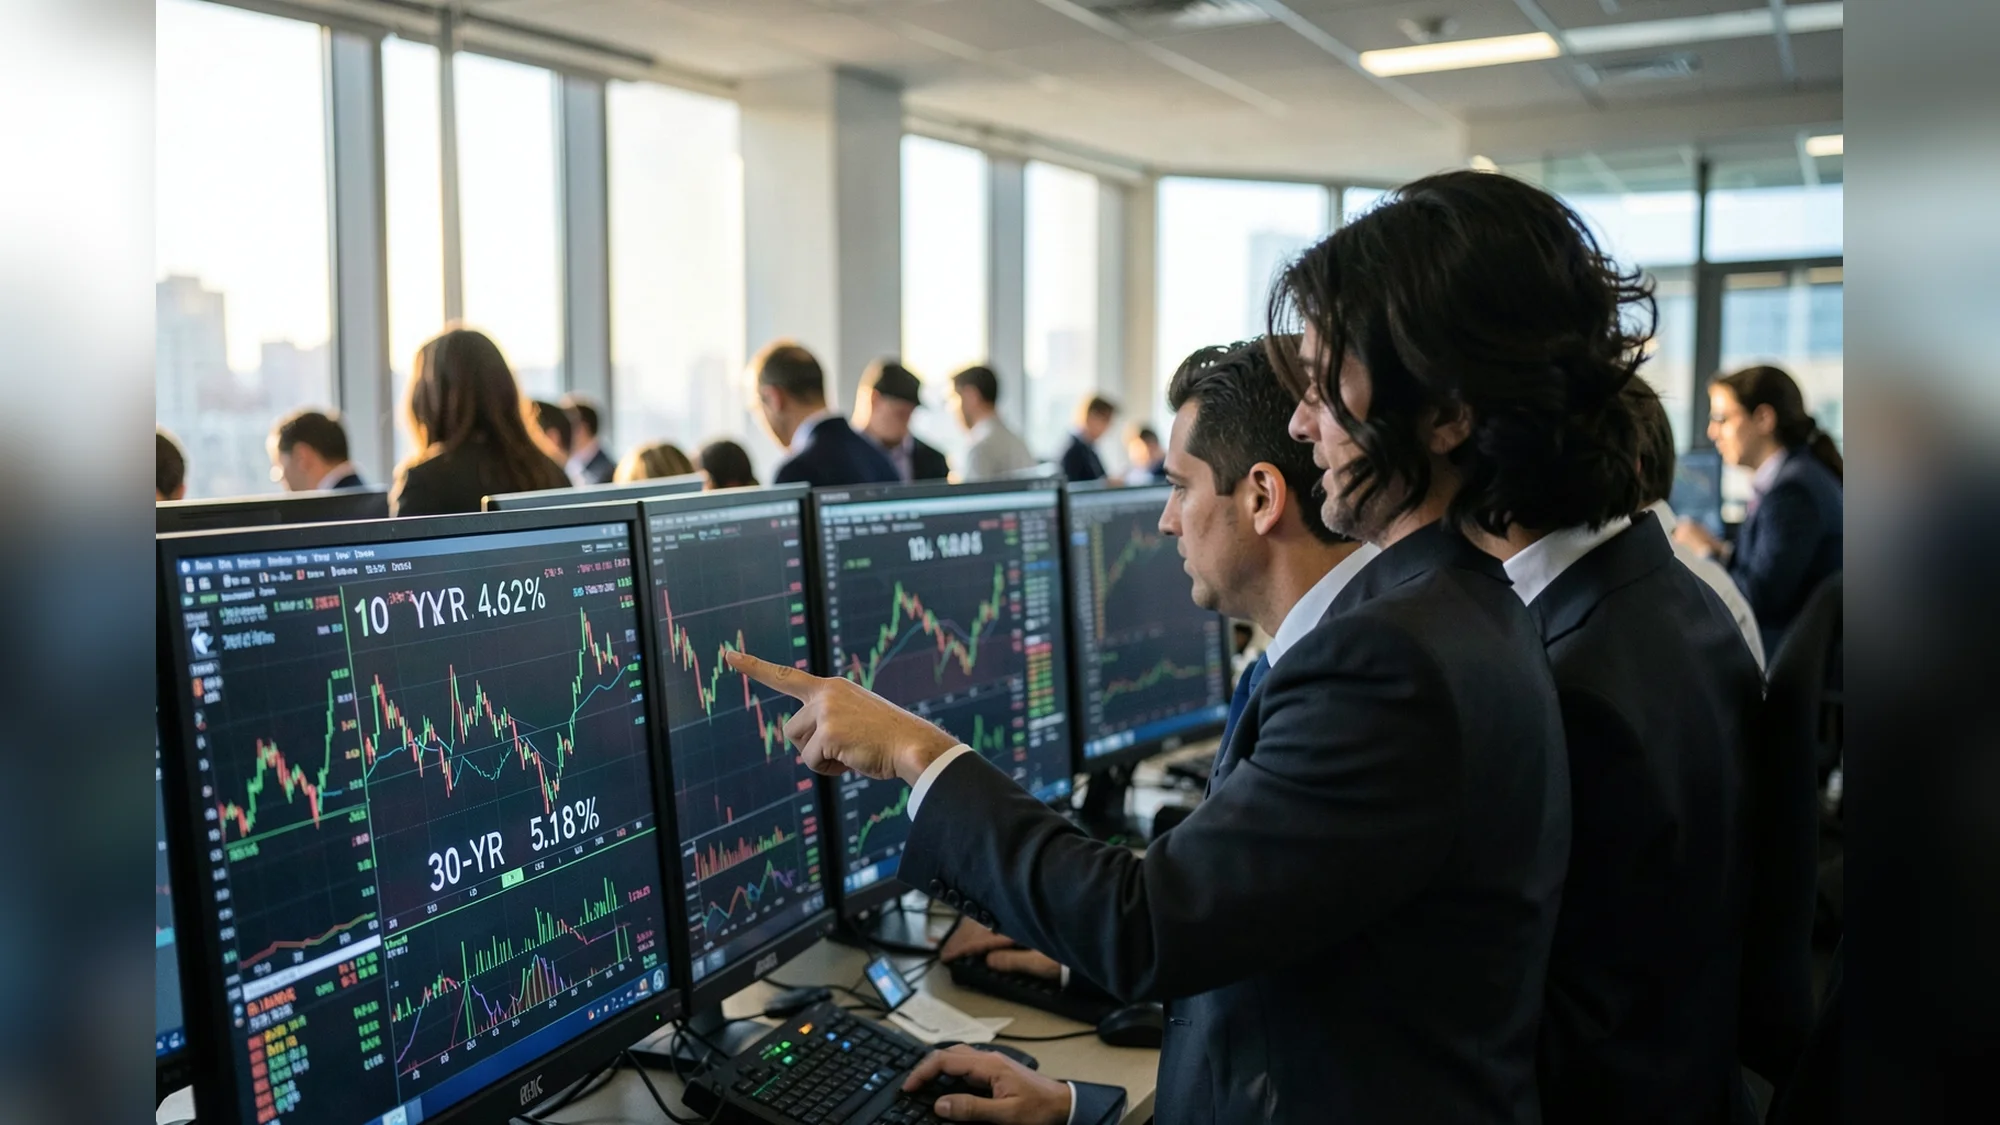
On the trading floor of a New York fixed-income desk, traders watched the 10-year Treasury creep higher as activity picked up on Thursday. The 10-year was at 4.62% in early trading and the 30-year near 5.18%, small moves that sit on a larger shift toward meaningfully higher clearing yields this year. Mehmet Berceren of Rosenberg Research argues that rising issuance, weaker demand from traditional buyers, and growing policy uncertainty have combined to lift the baseline for real interest rates globally. The next big data check is the July jobs report, due August 7, 2026.
In a special report titled "The real rates reckoning," Mehmet Berceren, senior market strategist at Rosenberg Research, laid out the case. He framed the move not as a short blip but as a structural recalibration of real yields, the inflation-adjusted rates that set funding costs for governments and large borrowers. Berceren said three overlapping forces are doing the work: heavier issuance of long-duration debt, a drop in demand from buyers who historically soaked up that supply, and elevated policy uncertainty that raises the premium investors require for locking in long-term exposure.
Wells Fargo Investment Institute charted the market reaction on August 6, 2026 and tied the higher-yield backdrop to recent economic indicators and supply dynamics. At 7:02 AM ET that morning Wells Fargo recorded the 10-year at 4.62%, up 0.01 percentage point from the prior session, the 30-year at 5.18% up 0.01, and the two-year note, which reacts most to monetary policy, at 4.20% up 0.02. Wells Fargo noted yields were mostly unchanged from the prior day, when the 10-year had been 4.61% and the 30-year 5.17%.
The data mix is messy for investors trying to price duration. The Automatic Data Processing National Employment Report for July showed private payrolls rose by 44,000, below expectations. The Institute for Supply Management's services PMI for July came in at 54.1, short of forecasts, while its prices-paid component unexpectedly jumped to 70.3. S&P Global revised its finalized services and composite PMIs for July slightly higher to 54.6 and 54.5, respectively.
Taken together, those prints point to services activity that's still expanding while input cost pressure is present.

Supply mechanics added pressure on money markets. Wells Fargo listed a heavy short-term Treasury calendar, with $110 billion in four-week bills and $100 billion in eight-week bills scheduled, a pattern that amplifies supply in the very short end. On the municipal side, Bloomberg's 30-day visible muni supply fell but remained above its 12-month average. The combination of larger federal issuance and still-elevated visible municipal supply matters because it forces investors to choose where to allocate scarce cash.
Berceren and the Wells Fargo note read that these pieces interact in a self-reinforcing cycle. First, higher issuance increases the stock of bonds that need buyers.
Second, when traditional demand from banks, insurers, and foreign buyers softens, dealers and other investors push yields up to clear that inventory. Third, policy uncertainty, including questions about future central bank moves and fiscal paths, raises the term premium investors charge to hold long-duration assets. The result, their analysis says, is a higher structural level for real yields than markets had priced earlier in the year.
That matters beyond traders marking desks. Real yields set a baseline for funding across the economy. If the baseline moves up, governments face higher interest costs and corporations, homeowners, and small businesses can see borrowing costs follow. Strategists who treat the higher yields as transient may find refinancing and budget math less favorable than expected if the new baseline holds.
Markets will get a fresh read on labor conditions on August 7, 2026 when the July jobs report is released. For investors trying to decide whether this is a pause within a downtrend or a step to a new normal, that payroll number will be a key input to how the Treasury curve is priced heading into the late summer.
Related Articles
- Treasury Yields Hold in Narrow Band Ahead of Fed Meeting
- American Airlines to Sell $1.14B Bonds Backed by 32 Planes
- U.S. sanctions shift: 60-day Jones Act waiver, pressure on Iran
The next scheduled datapoint is the July jobs report on August 7, 2026. Originally reported by marketwatch.com.
This article was created with AI assistance.


